TORQ
TORQ explains governed credit operations for digital and tokenized assets.
- 03 OCT 2026
- 5 min read
Credit rates and liquidity
A manager's pricing, capacity, and exit choices affect different participants. Use a simple facility scenario to see why the three decisions must be evaluated together.
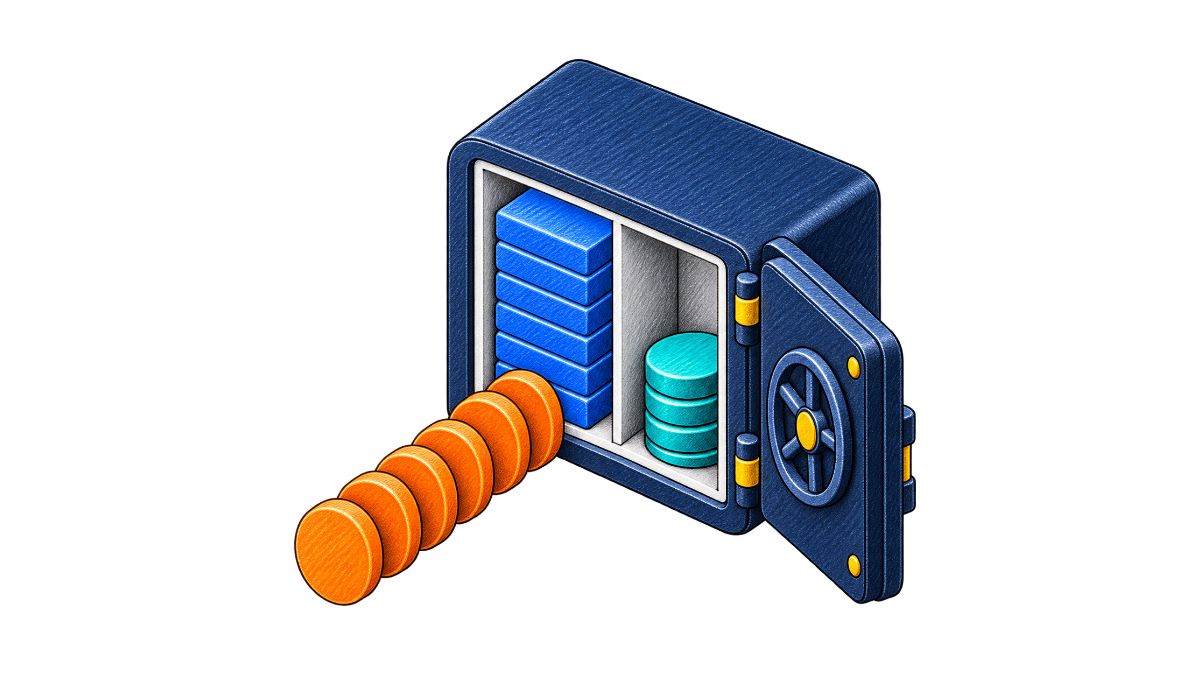
A credit vault has to support borrower draws and investor exits with the same finite capital.
Pricing can respond to utilization, but a higher rate does not itself put cash in the vault at the moment an investor asks to redeem.
Managers therefore need to review three linked policies: how much may be lent, how the floating rate responds to utilization, and what happens when valid exit requests exceed usable cash.
A USD 1 million facility example.
Assume a vault has USD 1 million of assets, with USD 700,000 lent and USD 300,000 in usable cash. The simple lent-to-assets ratio is 70%.
Now assume investors submit valid requests totaling USD 400,000 and there are no other cash sources or restrictions.
At most USD 300,000 can be paid from that cash today. The remaining USD 100,000 requires later usable inflows or another permitted liquidity action.
The fact that the loans accrue interest does not mean the next USD 100,000 is in the vault today.
If the manager had retained USD 400,000 cash before the requests, the same request could be covered in this simplified case, but only USD 600,000 would have been lent.
That difference affects both borrower capacity and the amount of capital earning loan interest.

What a utilization-based rate can and cannot do.
A floating-rate model can make additional borrowing more expensive as usage rises, subject to its actual formula and parameters. That may influence future demand, repayment incentives, and capital allocation.
It cannot guarantee when existing borrowers repay or when investors receive cash.
A facility with a steep rate response may protect available capacity differently from one with a flatter curve. It may also make borrower cost less stable.
The manager should model both normal utilization and a simultaneous draw-and-withdrawal stress, with the actual loan and vault terms.
- Keep more cash
- Potential benefit: More immediate capacity for valid exits.
- Cost or unresolved risk: Less capital available to fund loans.
- Lend more capital
- Potential benefit: More borrower capacity while loans perform.
- Cost or unresolved risk: Less immediate cash if investors request exit.
- Raise rates at high usage
- Potential benefit: Can change incentives and price scarce capacity.
- Cost or unresolved risk: Does not create immediate cash. Borrower cost rises.
The manager's stress review.
- Model valid redemption requests alongside the largest permitted borrower draws.
- Separate outstanding loan value, accrued interest, reserved cash, and cash usable now.
- Test rate changes at the actual utilization breakpoints and disclose who can change the parameters.
- Record the queue and partial-payment rules before investors enter, including the consequences of a recognized loss.
- Compare the model with the legal mandate, servicing capacity, and actual capital-provider needs.